Indorama Ventures
Executive Summary
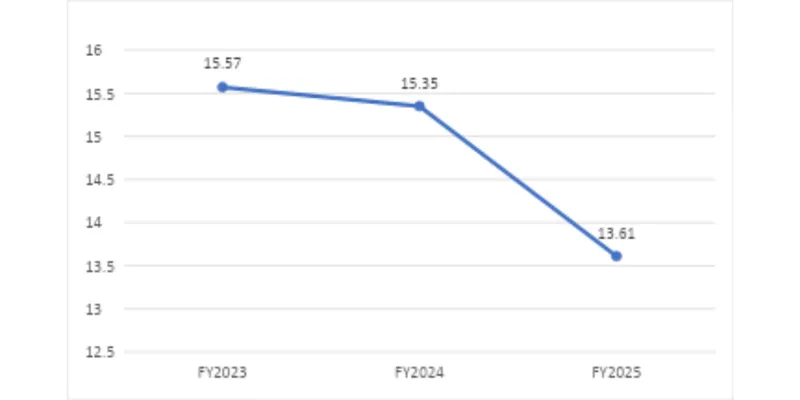
Indorama is a public limited company located in Bangkok, Thailand. The company was established in 1994 by Aloke Lohia. It engages in business within four segments, namely Combined PET and Packaging, Fibers, Indovida, and Indovinya. In 2025, Indorama had revenues worth $13.61 billion, which were not as good as those recorded in the previous year. Gross profit declined in 2025 because of reduced demand and sales of their goods. However, there has been an increase in EBITDA.
The Ratio Analysis shows that the company's liquidity is weak. It shows a net loss and high debt. Their inventory and assets are maintained, but efficiency can be improved.
Company Overview
Indorama Ventures Public Company Limited is a sustainable chemical company and a leading petrochemical company. The company is located in Bangkok, Thailand, and it was founded by Aloke Lohia in 1994.It is the world’s largest producer and recycler of PET resins. They conduct manufacturing operations at 114 locations in 32 countries. Its business operates in Combined PET and Packaging, Fibers, Indovida, and Indovinya. The company operates in the business segments of Combined PET and Packaging, Fibers, Indovida, and Indovinya.
Industry Overview
This firm is involved in petrochemicals and chemical manufacturing industries. This firm is also engaged in polyester fiber business through the fiber business segment. They supply the natural material, yarns, fibers, and technical textiles required by various industries including packaging, textile, automobile, healthcare, and consumer goods.
The PET and PBT resins market size is estimated to be USD 48 billion now and will achieve USD 64 billion by 2029. The growth rate is about 6%.
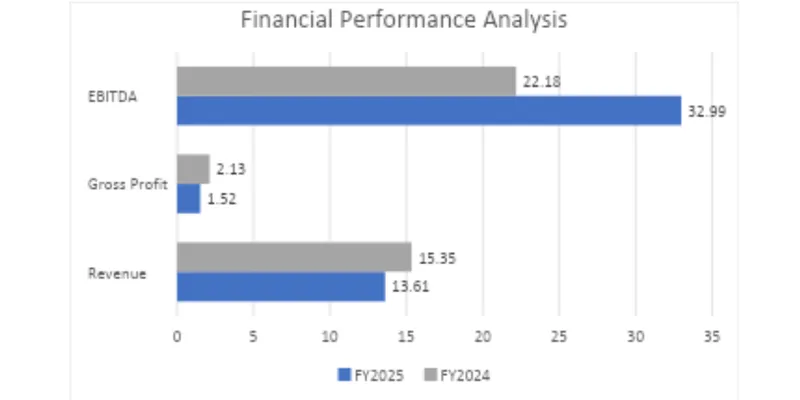
Year | Revenue (USD Billion) |
FY2025 | 13.61 |
FY2024 | 15.35 |
FY2023 | 15.57 |
Financial Performance Analysis
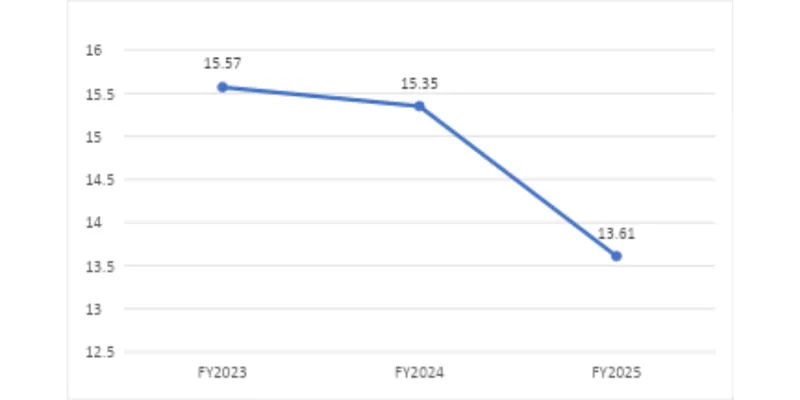
Particulars (USD Billion) | FY2024 | FY2025 |
Revenue | 15.35 | 13.61 |
Gross Profit | 2.13 | 1.52 |
EBITDA | 22.18 | 32.99 |
Key Financial YOY
Revenue Trend Over 3–5 Years
Interpretation
Revenue decreased because of weak demand in the market and price fluctuations in the company's business segments, while gross profit decreased due to lower sales of key products. However, EBITDA increased due to improved cost management and expenses.
Key Financial Ratio
Ratio Category | Formula | 2025 | Interpretation |
Current Ratio | Current Assets / Current Liabilities | 0.98 | Indicates adequate short-term liquidity, though current liabilities slightly exceed current assets. |
Quick Ratio | (Current Assets − Inventory) / Current Liabilities | 0.51 | Shows limited ability to meet short-term obligations without selling inventory. |
Gross Margin % | Gross Profit / Revenue × 100 | 11.14% | The company generated THB 11.14 gross profit for every THB 100 of revenue. |
Net Profit Margin % | Net Profit / Revenue × 100 | -1.54% | The company incurred a net loss of THB 1.54 for every THB 100 of revenue. |
Return on Equity (ROE) | Net Profit / Shareholders’ Equity × 100 | -5.36% | Negative ROE reflects losses and lower returns for shareholders. |
Debt-to-Equity Ratio | Total Debt / Shareholders’ Equity | 3.06 | Indicates a high dependence on debt financing. |
Interest Coverage Ratio | EBIT / Interest Expense | 0.42 | Operating profit was insufficient to comfortably cover interest expenses. |
Inventory Turnover | Cost of Sales / Inventory | 4.63x | Inventory was sold and replenished about 4.6 times during the year. |
Asset Turnover | Revenue / Total Assets | 0.84x | The company generated THB 0.84 of revenue for every THB 1 of assets. |
SWOT Analysis
Strengths | Weaknesses |
Global leader in PET production and recycling. | High debt levels and leverage. |
Diversified portfolio across packaging, fibers, and chemicals. | Profitability impacted by weak petrochemical market conditions. |
Extensive global manufacturing network and economies of scale. | Exposure to volatile raw material and energy prices. |
Opportunities | Threats |
Growing demand for recycled PET (rPET) and sustainable packaging. | Intense competition from global petrochemical companies. |
Expansion opportunities in emerging markets. | Fluctuations in crude oil and feedstock prices. |
Strategic acquisitions and partnerships for growth. | Economic slowdowns and stricter environmental regulations. |
Peer / Competitor Comparison
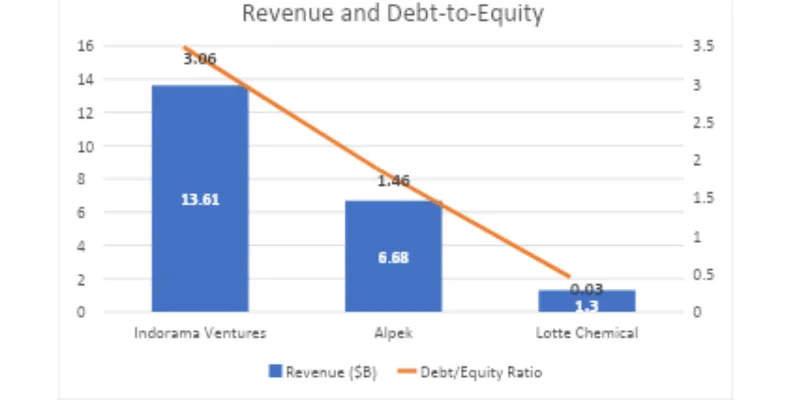
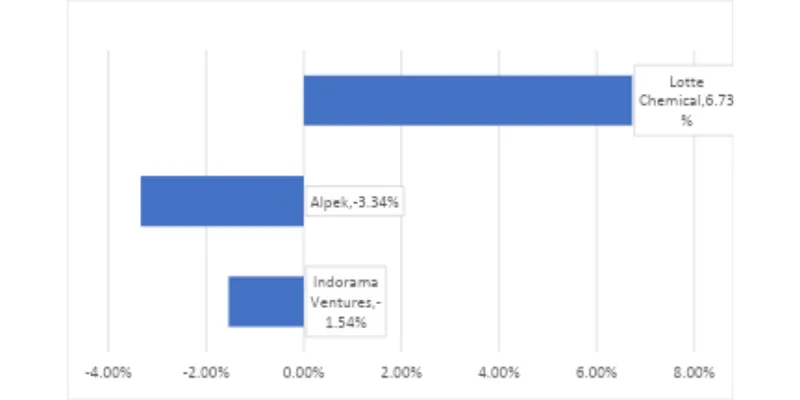
Particulars (FY2025) | Indorama Ventures | Alpek | Lotte Chemical |
Revenue ($B) | 13.61 | 6.68 | 1.3 |
Net Profit Margin | -1.54% | -3.34% | 6.73% |
Debt/Equity Ratio | 3.06 | 1.46 | 0.03 |
Conclusion and Recommendations
Indorama Ventures is a producer of PET and sustainable chemical products. The analysis shows that its revenue has decreased. In addition, the firm has negative net profit margins of -1.54%, hence is financially unstable. Despite its wide international footprint and diverse products, the company must focus on increasing its liquidity and profitability in order to improve its financial position.
References & Sources
- Indorama Official Website.
- Yahoo Finance - Indorama
- Yahoo Finance - Alpek
- Yahoo Finance - LOTTE Fine Chemical Co., Ltd. Financial Data.
- MS Excel - Charts