Don & Low
Executive Summary
Don & Low Ltd. is a manufacturer of technical textiles and operates under Thrace Group, its parent company. The report will consider the financial statements of the Thrace Group as a whole. In 2025, the parent company had a significant increase. Moreover, an increase in revenue, EBITDA, and net income is observed, which characterizes good work. It can be seen from ratios that there is a lack of liabilities in the firm, high liquidity, and efficient cost management.
Company Overview
Don & Low Ltd. manufactures high-performance woven and nonwoven polyolefin fabrics for industrial applications. It is located in Forfar, Angus (Scotland). It was established in 1792 by William Don. It was purchased in 1999 by the multinational Thrace Group. The company serves various markets, including construction, medical, agriculture, and filtration. By 2026, the company has completed approximately 234 years of operations.
Industry Overview
Don & Low Ltd. is a UK-based manufacturer of woven and nonwoven technical textiles. The company operates in the international market, providing high-performance synthetic textile materials. The company is recognized for its vertically integrated manufacturing operations and advanced polymer processing technologies like Spunbond & Meltblown Technologies and Woven Polyolefins. Some of the product lines manufactured by the company are Geotextiles, Industrial Textiles, Medical Nonwovens, Filtration, Protective, Artificial Grass Yarns, and Packaging Textiles.
As a subsidiary of Thrace Group, Don & Low does not release independent annual or quarterly financial statements. Instead, its financial performance is included in the consolidated financial statements of its parent company.
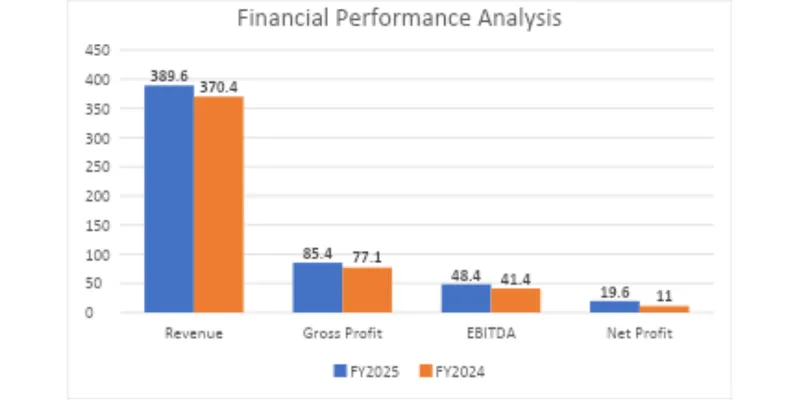
Year | Revenue (EUR million) |
FY2023 | 345.4 |
FY2024 | 370.4 |
FY2025 | 389.6 |
Financial Performance Analysis
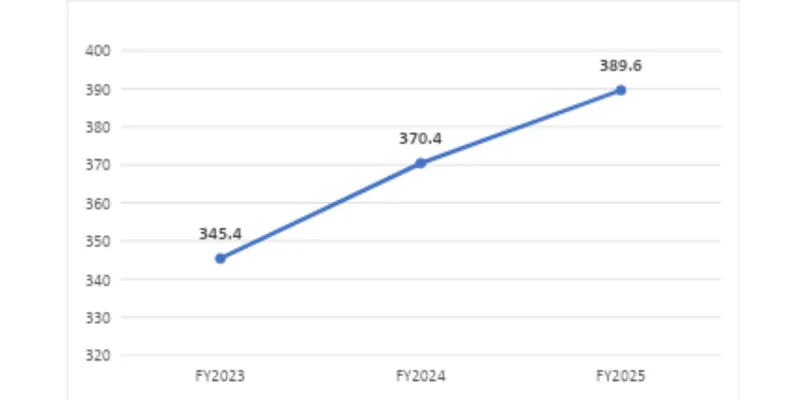
The following analysis is based on the consolidated financial performance of Thrace Plastics Group, the parent company.
Particulars (€ Million) | FY2025 | FY2024 |
Revenue | 389.6 | 370.4 |
Gross Profit | 85.4 | 77.1 |
EBITDA | 48.4 | 41.4 |
Net Profit | 19.6 | 11.0 |
Key Financial YOY
Revenue Trend Over 3–5 Years
Interpretation
There was growth in revenue due to the good performance of the firm. There was also growth in gross profit and EBITDA due to cost management and proper operations. There was growth in net income, an indication that the firm earned more from its operations.
Key Financial Ratios
Ratio Category | Formula | FY 2025 | Interpretation |
Current Ratio | Current Assets / Current Liabilities | 1.6 | The ratio reflects a healthy liquidity position and the ability to settle short-term liabilities. |
Quick Ratio | (Current Assets − Inventory) / Current Liabilities | 0.9 | Shows adequate liquidity without relying on inventory sales. |
Gross Profit Margin % | Gross Profit / Revenue × 100 | 21.9% | Reflects good control over production and operating costs. |
Net Profit Margin % | Net Profit / Revenue × 100 | 5% | Indicates moderate profitability from sales. |
Return on Equity (ROE) | Net Profit / Shareholders’ Equity × 100 | 7% | Reflects a moderate return generated for shareholders. |
Debt-to-Equity Ratio | Total Debt / Shareholders’ Equity | 0.21 | Reflects low financial leverage and a strong capital structure. |
Interest Coverage Ratio | EBIT / Interest Expense | 7.2 | This indicates a strong capacity to meet interest payment obligations. |
Inventory Turnover | Cost of Sales / Inventory | 3.5 times | Indicates efficient inventory management. |
Asset Turnover | Revenue / Total Assets | 0.87 times | Assets are being utilized effectively to generate revenue. |
SWOT Analysis
SWOT analysis is based on Don & Low's operations within the Thrace Group and the overall technical textiles business environment.
Strengths | Weaknesses |
Strong global presence across multiple countries and markets. | Profit margins remain relatively moderate. |
Diverse product portfolio in technical fabrics, packaging, and agriculture. | Dependence on raw material prices affects profitability. |
Healthy liquidity position and low debt levels. | Operations are exposed to fluctuations in energy and transportation costs. |
Opportunities | Threats |
Expansion into new markets through acquisitions and investments. | Intense competition in the technical textiles and packaging industries. |
Growing demand for sustainable and recyclable products. | Volatility in raw material and energy prices. |
Increasing applications of technical textiles across industries. | Economic slowdown and geopolitical uncertainties may affect demand. |
Peer / Competitor Comparison
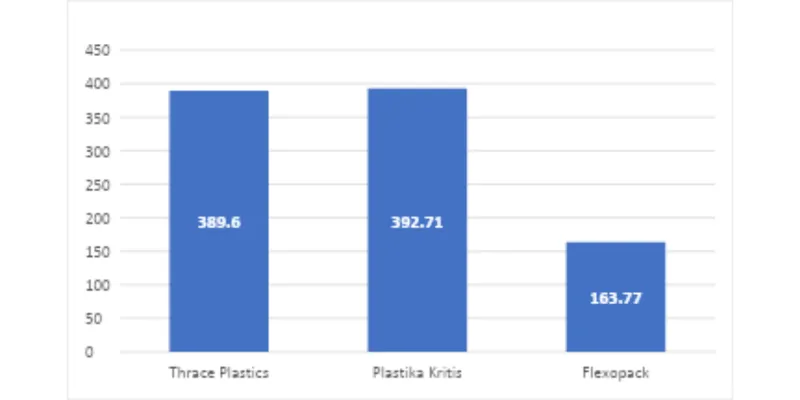
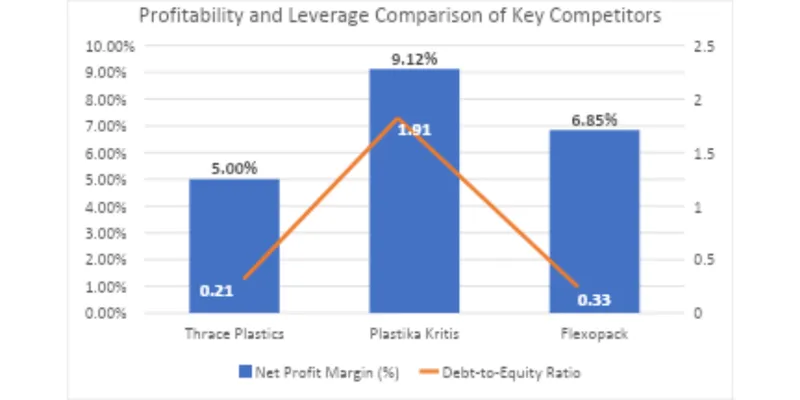
Company | Revenue (€ Million) | Net Profit Margin (%) | Debt-to-Equity Ratio |
Thrace Plastics | 389.6 | 5.0% | 0.21 |
Plastika Kritis | 392.71 | 9.12% | 1.91 |
Flexopack | 163.77 | 6.85% | 0.33 |
Conclusion and Recommendations
Don & Low specializes in the production of technical textiles. Being the division of the Thrace Group, this organization has become globalized and technologically advanced.Since the financial information of the company is not available, the analysis is based on the consolidated financial statements of the Thrace Group, which is the parent company. The year 2025 saw an increase in revenue, EBITDA, and net income for Thrace Group.
References & Sources
- Thrace Group Annual Report 2025
- Thrace Group Annual Report 2024
- Don & Low Official Website
- Thrace Group Official Website
- Plastika Kritis Annual Report 2025
- Flexopack Annual Report 2025
- Microsoft Excel – Charts, Graphs and Ratio Analysis